The evidence your auditor signs
Structured 2013 COSO assessments, traceable evidence, and action plans with assigned owners: Your firm closes the period with data, not just a report.
- Gap Analysis in 3 Weeks
- Traceable evidence starting with the first response
- Each gap has a plan, an owner, and a deadline
«Stamp seal» by Hittite maker, ca. 17th–16th century BCE, public domain (CC0), via The Metropolitan Museum of Art
- 3 months → 1 month
- End of the evaluation period Fuente: objetivo de producto
- 3 weeks
- Gap Analysis Fuente: medible
- 1 day
- Evidence Sampling Fuente: medible
- 120–200 hours
- Senior Project per Quarter (12 processes · 4 evaluations) Fuente: estimación modelada
Spreadsheet cost is never invoiced
Internal control assessments are scattered across spreadsheets and emails. No one knows what changed, when, or why.
The period closes with undocumented gaps, and the evidence is reconstructed later, when it can no longer be recovered. The external auditor’s findings are recorded in the report that you sign, and it bears your name, not the system’s.
| Control | Owner | Evidence | Status |
|---|---|---|---|
| Revenue | — | #REF! | Open |
| Reconciliation | J. Ruiz | email 08/12 | Review |
| Inventory | M. Paz | phone photo | Seen |
| Vendors | — | — | — |
| Period total | — | — | 2 of 4 |
From the 2013 COSO Framework to the Signed Report
-
5 components
Control environment, risk assessment, control activities, information and communication, and monitoring.
-
17 principles
Each component is evaluated based on its principles, with a grade assigned for each question.
-
Maturity and Plans
The rating is converted into a maturity level and gaps; each gap triggers a plan with an assigned person and a deadline.
-
Reports
The series delivers the same level of maturity seen on screen, along with the evidence to support it.
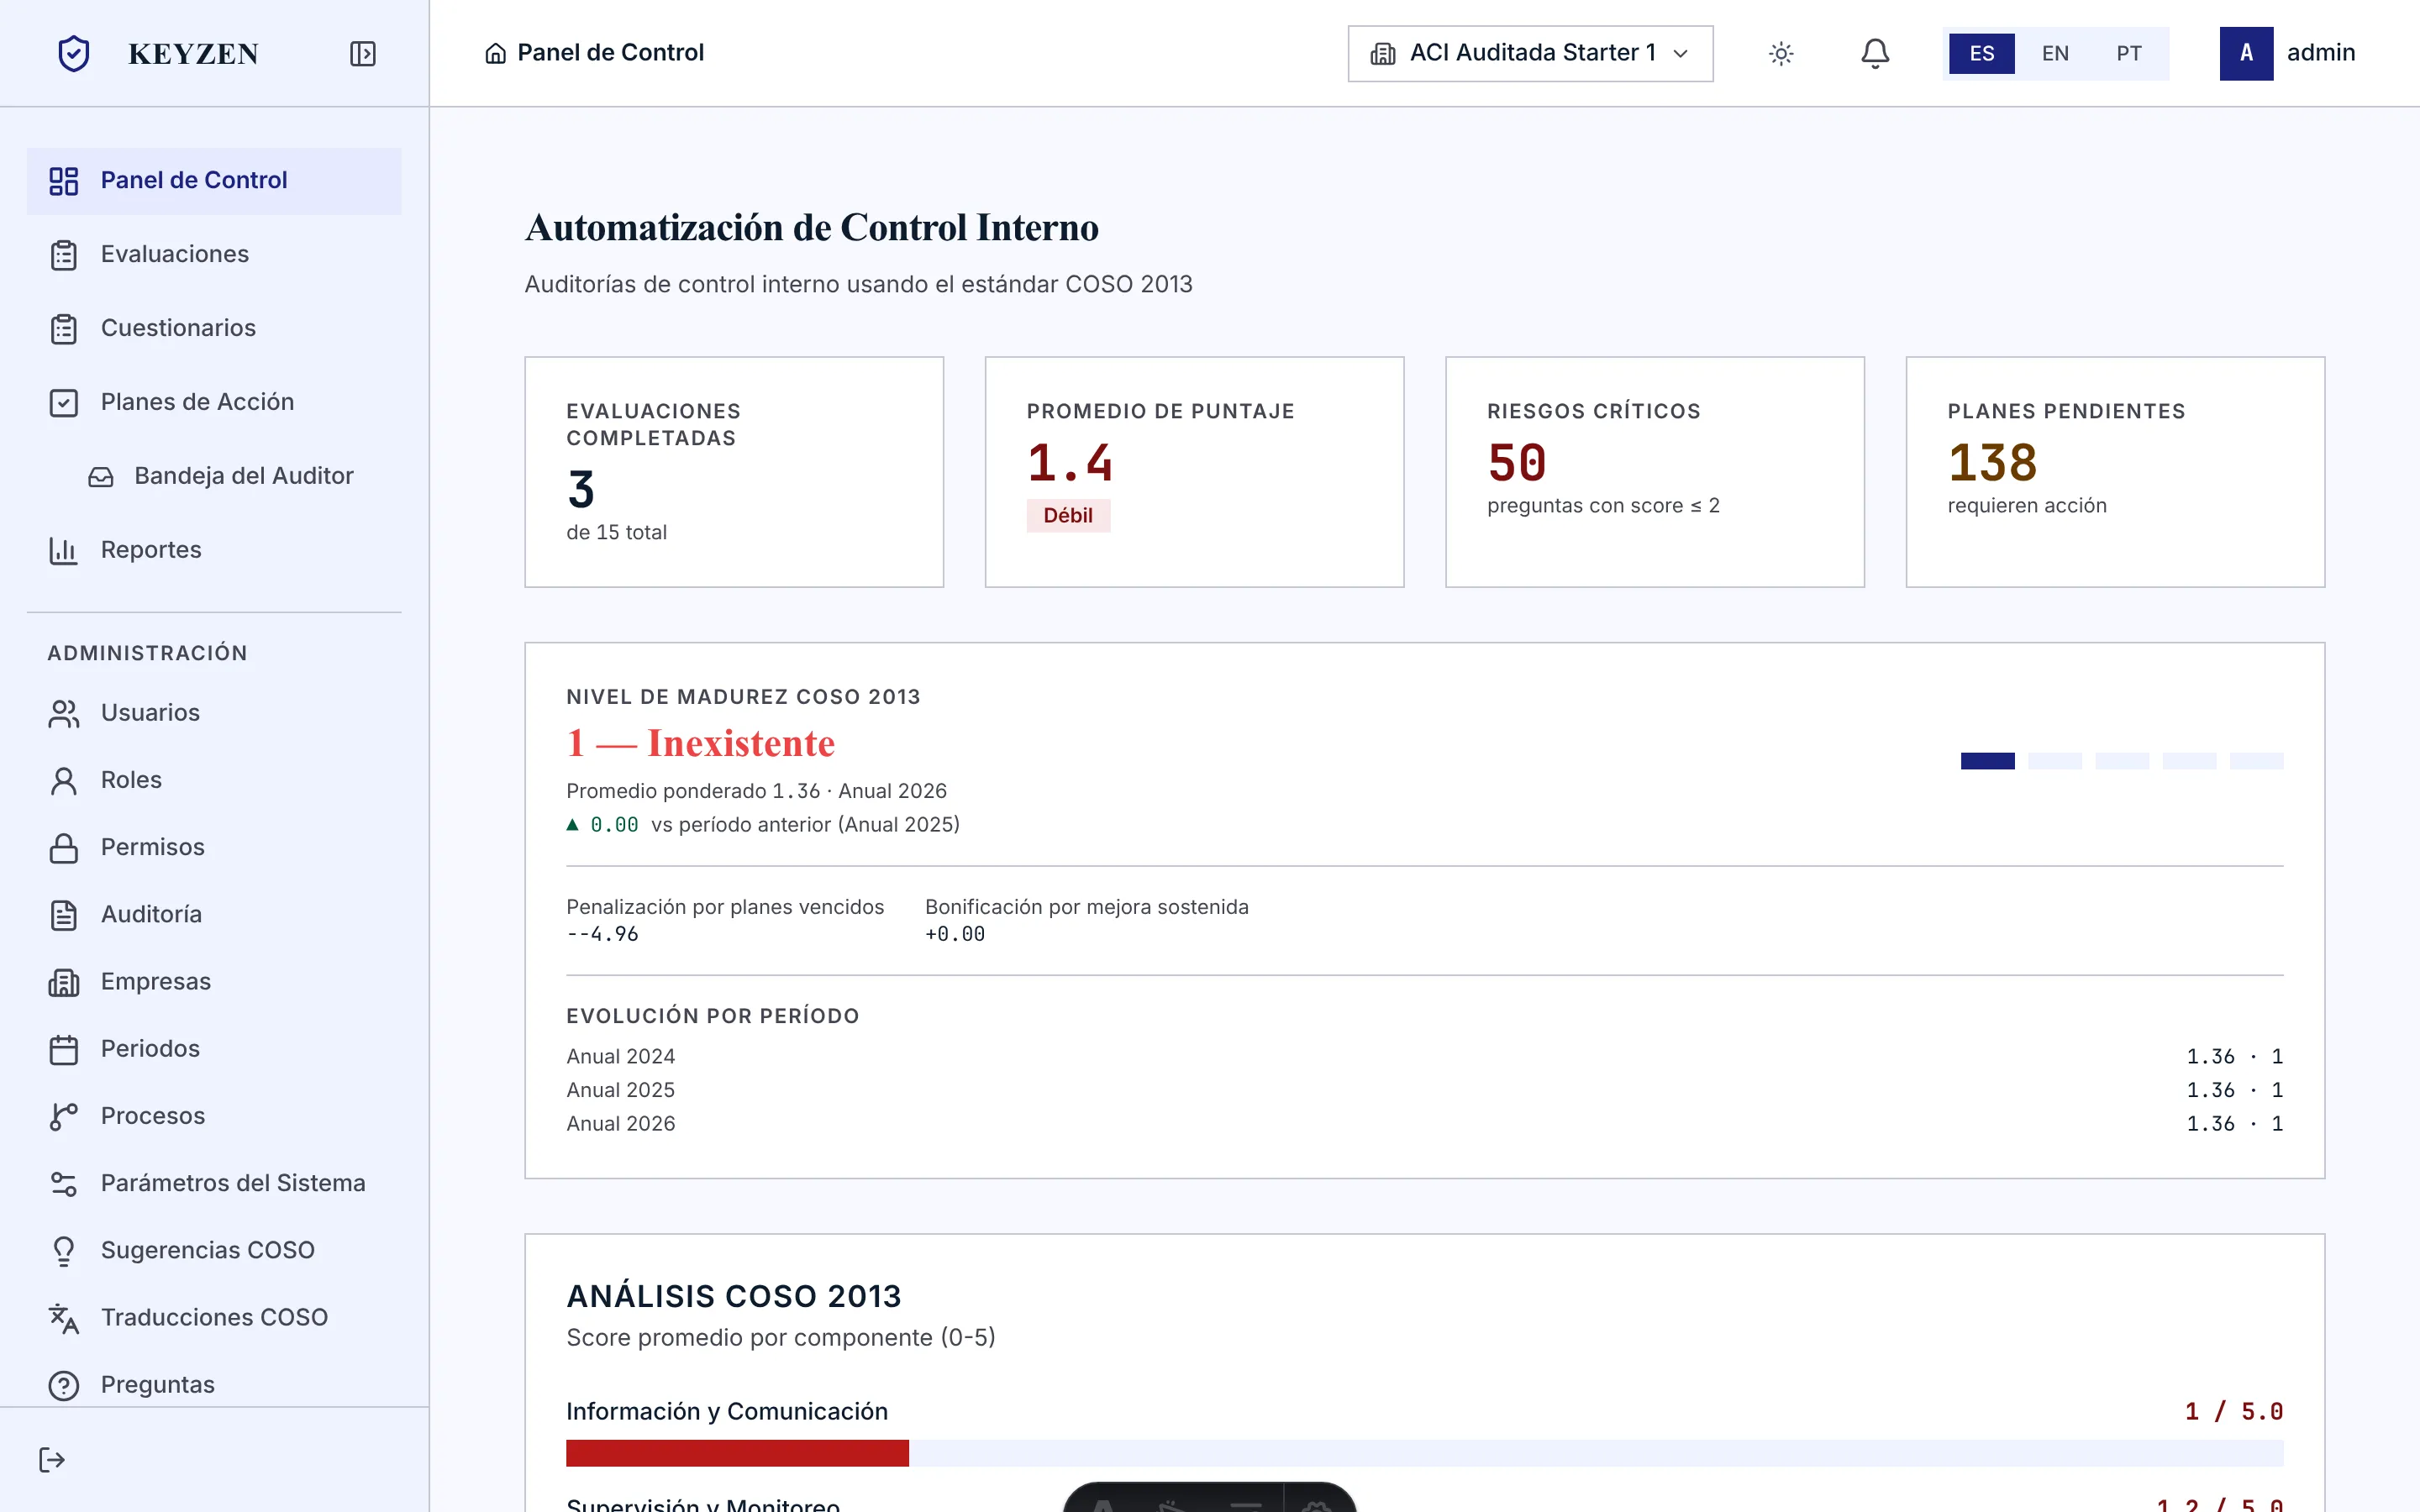
This is what the period report looks like
The same maturity figure you see on screen goes into the report: per component, with its trend and the penalty for overdue action plans in plain sight.
Each conclusion retains its origin
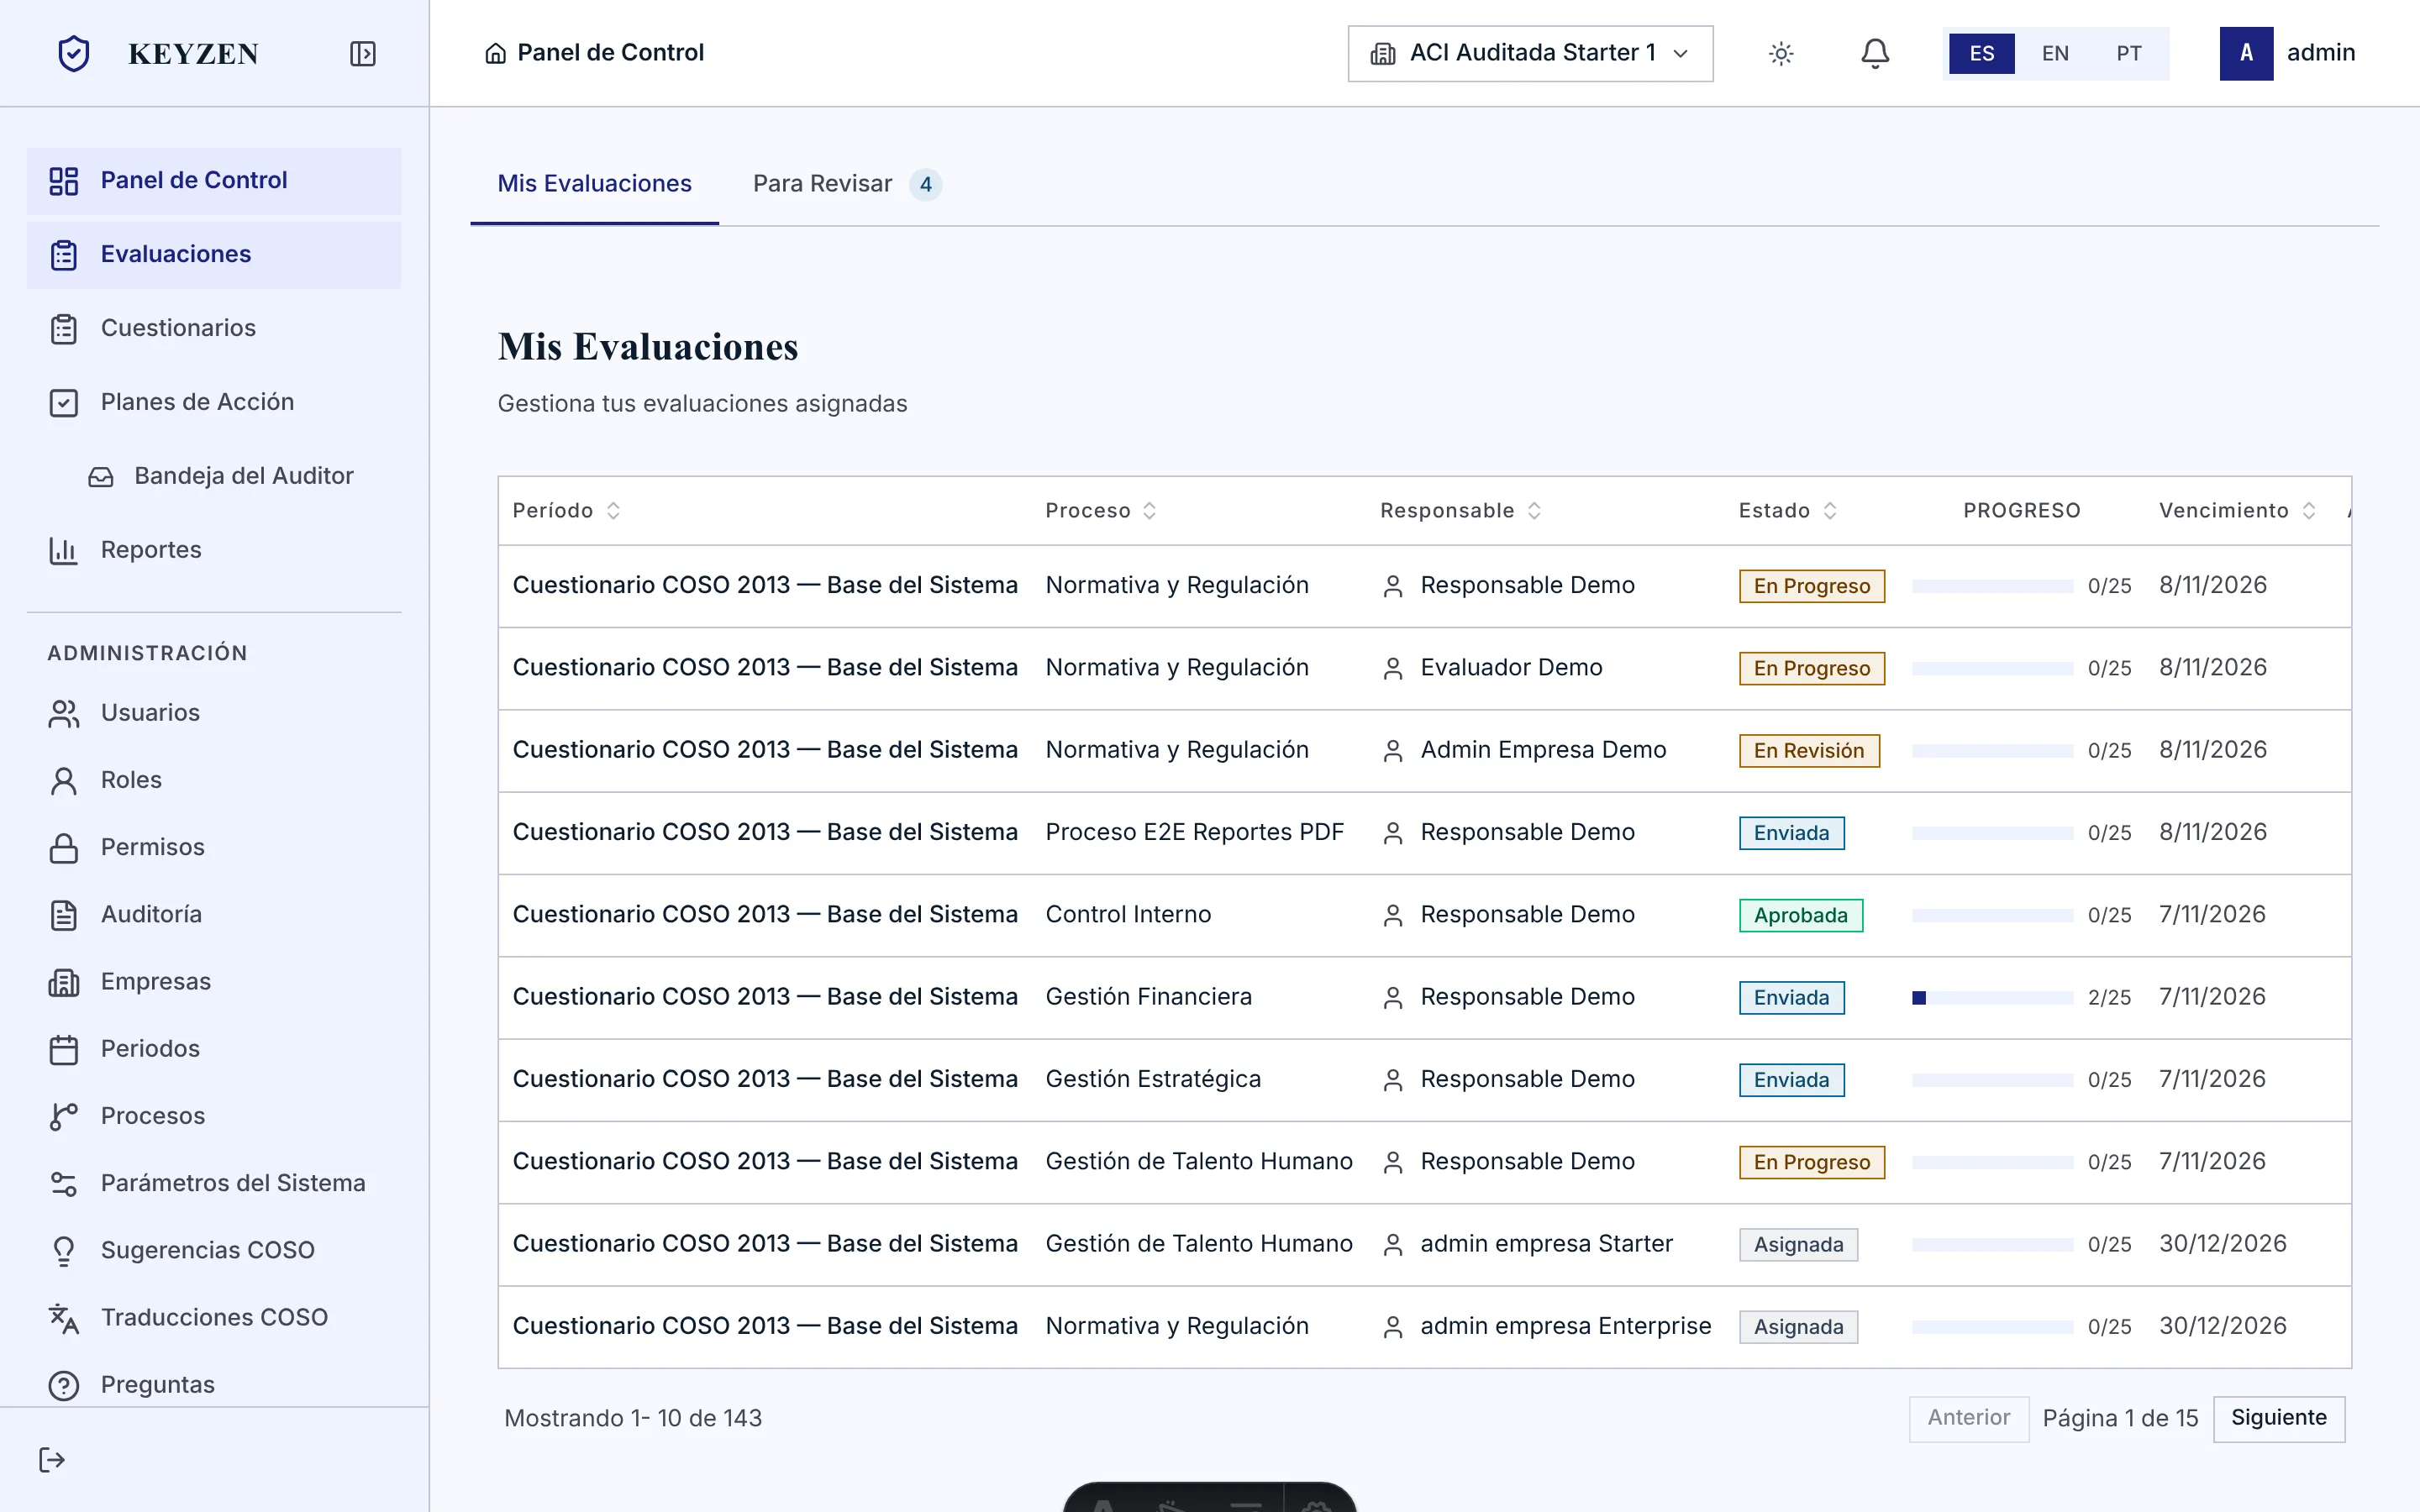
The entire chain is preserved and can be traversed in either direction. Each rating records who made it, when, and what its previous value was.
-
Evaluation
The person in charge completes the questionnaire for the assigned process, including their rating.
-
Evidence
Each response may include supporting evidence, along with the date and author.
-
Discovery
A score below the threshold is classified as an identified gap.
-
Plan
Each gap is addressed with an action plan that includes a person in charge and a deadline.
-
Report
The periodic report cites the evidence and the plan that support it.
Four ways to close the period with data
- Control environment
- Risk assessment
- Control activities
- Information and communication
- Monitoring activities
- 5 components · 17 principles
Assessment by Component and Principle
The complete, structured framework. You don't configure it—you just use it.
- From the very first response
Traceable evidence
Each conclusion includes who, when, and what evidence.
- No orphaned gaps
Action plans with an assigned person and a deadline
Every issue is addressed in the report, along with the person responsible and a deadline.
- Up to 30 companies
Companies Audited Under a Single Account
A firm manages its entities through a single registry.
For those who sign the internal control period
Audit Firms
They evaluate their clients' internal controls and are responsible for the conclusion.
Internal Control Areas
They maintain their own organization's internal control system.
Finance Department
You need the maturity figure and the open gaps before the close.
Frequently Asked Questions
Cost
Another platform represents a new cost in an adjusted year.
The comparable cost isn't the license—it's the senior staff hours that are currently being spent on reconstructing evidence.
Start with a single process: measure the close time for the first period before extending it.
Alternative: If, during the first period, the diagnosis does not reduce the turnaround time, the process is halted at no cost.
Moment
Switching tools in the middle of an open period is inconvenient.
The open period is precisely when the evidence is lost: starting there doesn't reset it—it captures it.
The initial upload is a process, not the entire file: the rest is added in the next period.
Alternative: Evaluate the product using a closed-loop process and compare it with the manual reconstruction.
Trust
No new platform comes with a customer history.
I'd rather not show you specifications that don't exist: each capability is verified against its specification.
Every statement on this page can be verified against the product agreement.
Alternative: Ask for details about any capacity before making a decision.
Complexity
An internal control system is not office software.
The product is based on the COSO 2013 framework; you don't configure the framework—you use it.
Five components and seventeen principles have already been mapped out.
Alternative: The founding group is receiving support during the startup phase.
Competition
There are large auditing suites on the market.
The suites cover the entire scope of the engagement; this addresses the internal control work required by COSO 2013.
The scope is deliberately limited: evidence, gaps, plans, and reports.
Alternative: If your company needs the full suite, I'll let you know before you evaluate it.
Start with one process and measure the close
Early access for a founding group of firms. We start with a single process: if the assessment does not reduce your closing time during the first period, it is discontinued at no cost.
Each capacity listed on this page has been verified against its technical specifications and is auditable.